Freeport Approves US$4.5 Billion Bagdad Expansion
Freeport's Bagdad approval targets added copper from mid-2030, with a multiyear construction bill arriving before the new production.
 by Dominic Rhee2 min read
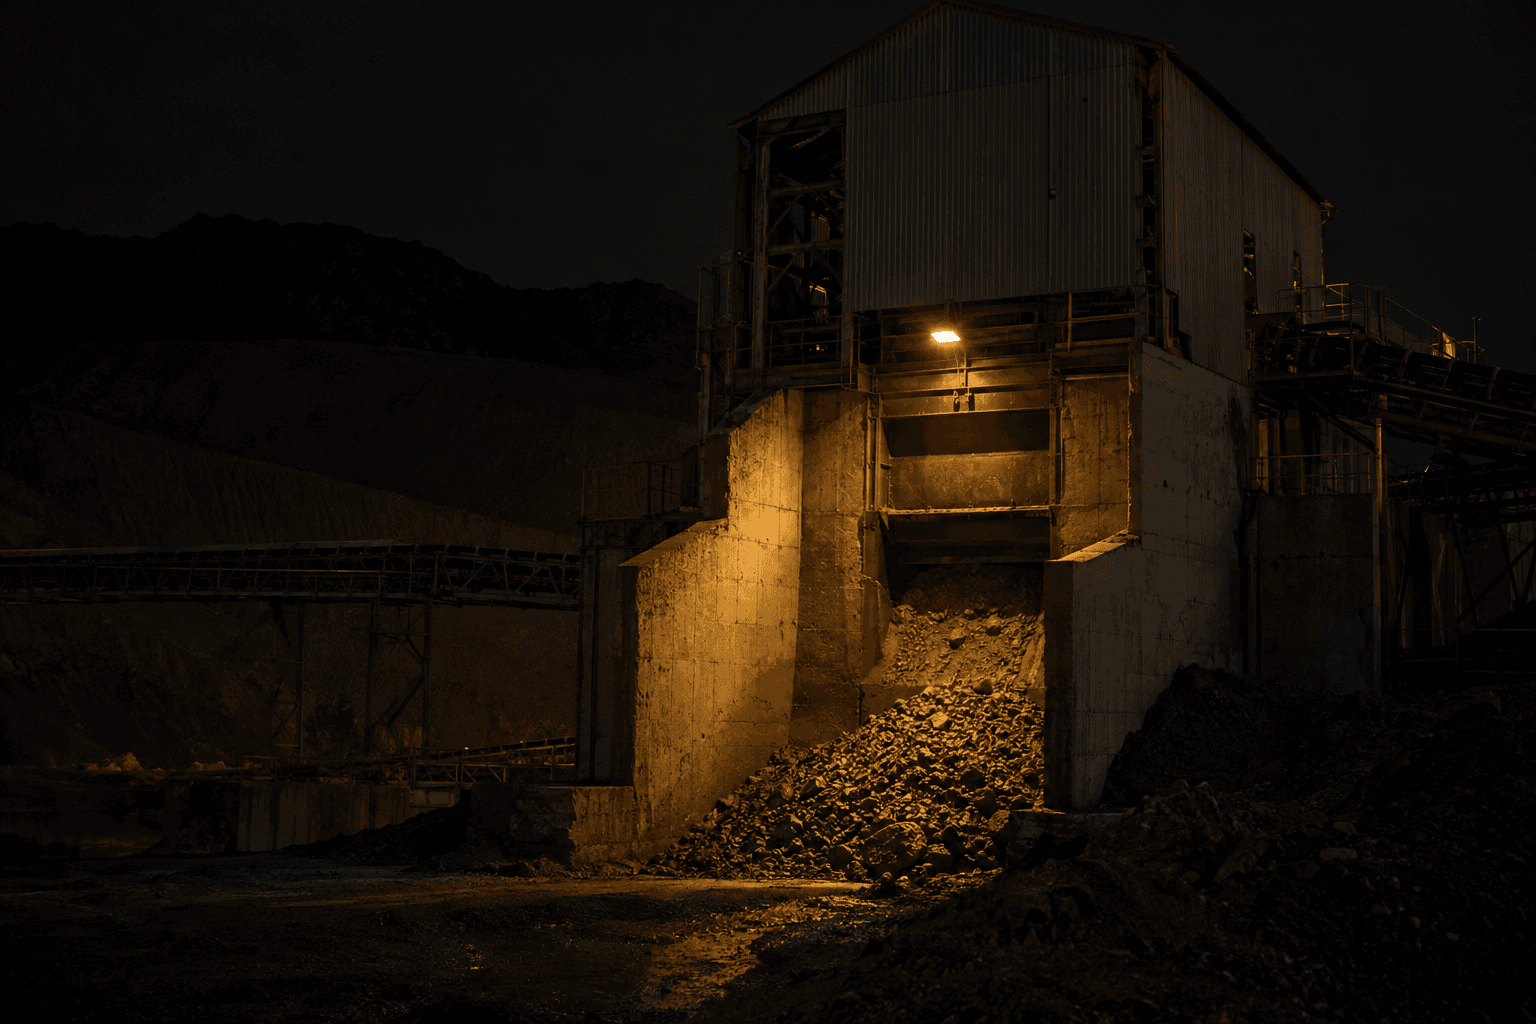
Freeport-McMoRan (NYSE: FCX) has approved a US$4.5 billion expansion of its wholly owned Bagdad copper and molybdenum mine in northwest Arizona, according to its November 4, 2026 announcement. The board's decision gives FCX holders a defined investment in future U.S. production. We now have a construction budget and a production target to judge, with initial production expected in mid-2030.
The expansion would add approximately 225 million pounds of annual copper production, according to Freeport's November 4 project highlights. Long-term annual copper output would exceed 400 million pounds. Molybdenum production would also increase, by approximately 12 million pounds annually. The new concentrator, which separates valuable minerals from ore, would add about 115,000 metric tons of daily nameplate processing capacity. That is equipment capacity, so we should judge eventual delivery by actual metal production. For your shares, the upside comes from expanding an existing operation, with new processing facilities and supporting infrastructure still to build.
The cash commitment arrives ahead of that output. Freeport's November 4 spending schedule allocates approximately 20% of project costs to 2027. Another 30% to 35% is expected in 2028. The balance is spread across 2029 and 2030. Freeport is advancing engineering, procurement planning and early works, and says the project spending will enter its updated capital expenditure outlook. It will classify that spending as discretionary under its financial policy. How much cash will FCX have left after investment? We need the revised company budget to assess that, because today's project total is spread across several years.
Freeport expects an approximately 20% reduction in Bagdad's long-term unit net cash costs, supported by scale, technology and molybdenum by-product credits, its November 4 release says. It describes project break-even economics at copper of approximately US$4.00 per pound, together with molybdenum at US$20 per pound. Those are project assumptions rather than quoted market prices. You cannot assess the economics using copper alone when the company also relies on molybdenum revenue. We would treat the cost reduction as a target, because both execution and the value of those by-product credits will influence the eventual result.
In Freeport Lowers Copper Sales Outlook, we focused on shipments, cash conversion and the investment bill. Bagdad adds a longer-term production opportunity to that cash allocation test. The company cautions that inflation and cost escalation could change the construction estimate. A larger future copper business can reward the investment, but FCX must carry the construction spending before the added output generates revenue. Approval therefore gives you a clearer growth plan while leaving the funding burden and construction performance to be tested.
Our next checkpoint is Freeport's updated capital expenditure outlook, which we will look for by year-end 2026, against the initial-production target of mid-2030.
Seek the truth and be prepared,
Equedia News
Sources
- Freeport-McMoRan, Bagdad expansion approval, HTML release, November 4, 2026
- Freeport-McMoRan, Bagdad expansion approval and project highlights, PDF, November 4, 2026
- Equedia News, Freeport Lowers Copper Sales Outlook, October 27, 2026
Disclaimer: This letter is for informational and educational purposes only and does not constitute investment advice. Past predictions and performance are not indicative of future results. Please see our full terms of use and disclaimer at equedia.com.